In short: with the Home Office also now reported to be facing a large IR35 bill, the Cabinet Office’s £38.5m recent IR35 bill comes down to the same thing that catches out most hirers: a lack of knowledge of how IR35 works, and/or a lack of joined-up thinking in the procurement and management team. Address these things and using outside-IR35 contracts will be much safer, providing a solution to hirers and contractors alike.
What happened at the Cabinet Office?
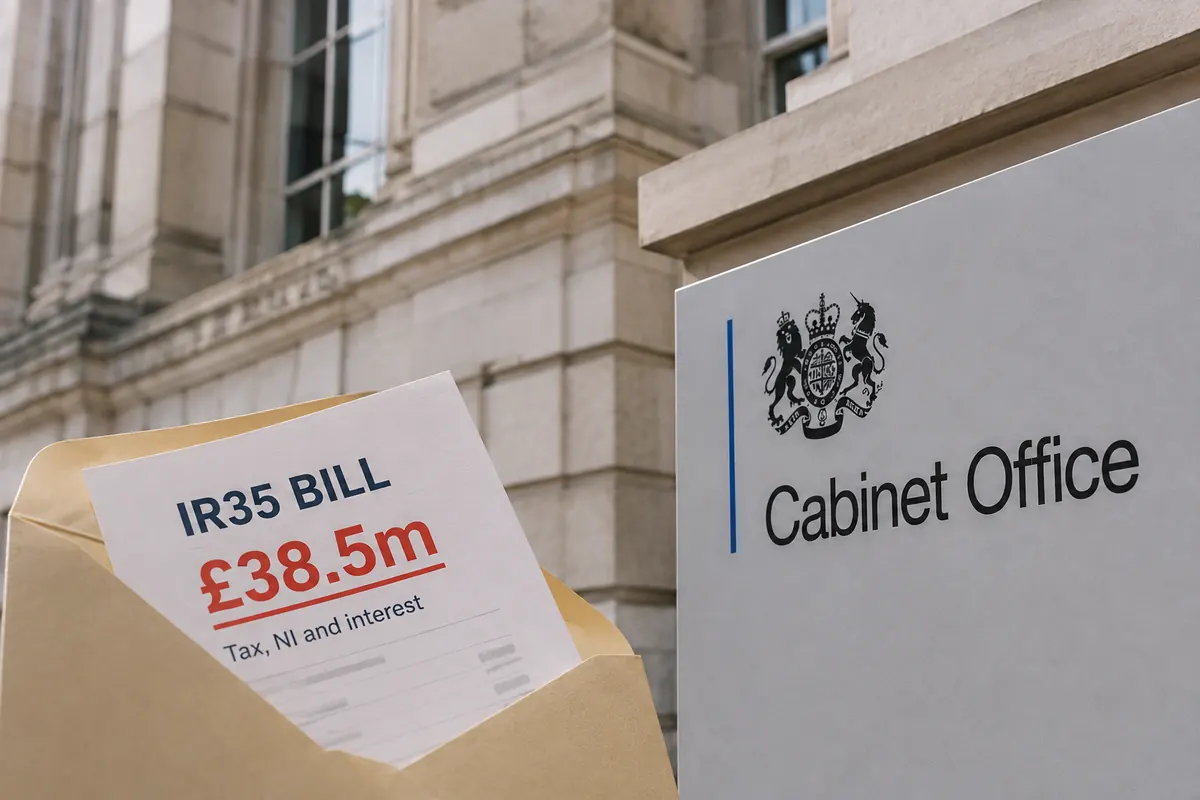
HMRC has concluded that the Cabinet Office failed to take reasonable care when applying the off-payroll working rules (IR35) to contractors engaged since April 2017. The department has set aside £38.5m for unpaid Income Tax, National Insurance and interest, and a penalty of up to £8.9m could follow.
This outcome can only mean that contractors were treated as outside IR35 when they should have been inside, so PAYE and NiC amounts that should have paid to HMRC were not so paid.
In nearly three decades of advising on IR35, we have found the cause for hirers getting it wrong is almost always one or all of three things.
Cause 1: Lack of Knowledge
The core of IR35 is deemed employment: the hypothetical – would the contractor be an employee if engaged directly? Many decision-makers do not understand how that works in practice. In our two articles from 2020 and 2021 IR35 Made Easy and IR35 Made Easier we explained the key practical question: is the contractor subject to the direction, supervision or control (SDC) of the hirer? The points we made in those articles have not changed.
Hirers can also be confused when they use HMRC’s Check Employment Status for Tax (CEST) tool. This is only as good as the responses provided, and the same applies to other online assessment tools. Answer the questions wrongly, or rely on the result when the answers do not match how the work is really done, and you are a hostage to fortune.
Cause 2: No joined-up thinking
Many hirers use their procurement team to bring in contractors. Procurement’s job is to get the right person in to do the work. Employment status is not their area; that should sit with HR.
HR may not be involved at all. Even when it is, HR will not necessarily know how project manager intends to run the work. The project manager is probably not concerned with tax status issues. So the people deciding IR35 status often have no real idea how the contractor will actually be handled day to day. Each of procurement, HR and project management see part of the picture, and nobody sees the whole when the decision to assess outside IR35 is made.
This lack of joined-up thinking can be fatal in the event of an IR35 investigation resulting from an outside IR35 assessment backed by use of an outside IR35 contract.
Cause 3: Over reliance on substitution
Too much reliance can be placed on substitution clauses in the contract. This is often seen as the ‘must have’ requirement for IR35 tax confidence, but must be treated with caution. Unless it lives in the real world, often missing in many arrangements, a substitution clause can provide a false sense of security. Such a clause can be relied upon only if the contractor has the right to, and can realistically provide, someone else to do the work without objection from the hirer.
The pressures that make it worse
The temptation to use outside-IR35 contracts is influenced by three pressures:
- contractors want to work outside IR35 to save tax, which can also mean lower day rates
- hirers are tempted to save employer National Insurance, which rose in April 2025
- engaging a contractor on the face of it reduces the risk of employment rights arising.
All three are real. None of them is a reason to risk liability under IR35.
How to get it right
The work, and nothing else, decides whether a contractor can safely be engaged outside IR35. A hirer who could be liable for IR35 taxes should be satisfied that:
- the thinking is genuinely joined up, so everyone involved in hiring and managing the contractor knows they cannot direct, supervise or control them, namely hands on manage the contractor
- the work is a genuine, discrete requirement that ends when it is completed or the work is terminated earlier
- the contractor can get on with the work subject only to necessary instructions.
Use the right contract
Get these aspects right and the work will fit the bill; use of an outside IR35 contract is then not only fully justified, but crucial. This should properly reflect the work arrangement rather than be a template that focuses on the tax position.
Who carries the risk?
Public sector bodies, whatever their size, and medium and large private sector hirers must decide IR35 status and take reasonable care doing so. Small private sector hirers are exempt; there, the contractor’s own company carries the risk.
Where an agency pays the contractor, it must operate PAYE on inside-IR35 engagements unless the hirer is exempt, so a large or medium-size client’s poor IR35 status decision quickly becomes the agency’s problem too. The agency will normally be HMRCs first port of call, leaving the agency having to use its only defence, that the client didn’t take reasonable care. Even if that argument is successful a claim by HMRC against the hirer may still result in the supplying agency’s liability if there is a tax indemnity clause in the agency to client contract.
What this means for recruitment agencies
Those agencies that help their clients close the knowledge gap and encourage joined up thinking between procurement, HR and project management will be the winners when it comes to placing outside-IR35 contractors. This means that agencies should be aware of the potential failings within a hirer’s organization and address them before relying on an outside IR35 assessment. Agencies that follow this path should be well placed to promote their approach to hirers and contractors alike.
Frequently asked questions
Why did the Cabinet Office get IR35 wrong?
HMRC found it failed to take reasonable care in making its various outside IR35 status assessments, which were incorrect. In our experience, that almost always comes from a lack of knowledge of how IR35 works or a lack of joined-up thinking between procurement, HR and the managers running the work.
Is HMRC’s CEST tool enough on its own?
No. A CEST result only helps if every answer reflects how the work is actually done, meaning that there should always be joined up thinking. This is the same for every online tool that aims to determine IR35 status.
Do small businesses have to decide IR35 status?
No. Small private sector clients are exempt, and the contractor’s company decides instead. Public authority bodies must decide status whatever their size.
Need help with IR35?
To get up to speed on how IR35 works, for training on IR35 or for contracts that properly reflect an outside-IR35 engagement, call us at Lawspeed on 01273 236236, or email to info@lawspeed.com.
Why Lawspeed
26 years of advising on IR35, presenting IR35 masterclasses, and producing effective IR35 friendly contracts for use by supply agencies, hirers, and contractors.
If you have any questions on the above then please call the team on tel: 01273 236236 to discuss how we can support you.
Adrian Marlowe – CEO